Using equity to fund a second home in Australia is often simpler than most homeowners expect, but understanding the numbers is critical before getting started. This guide breaks down how usable equity is calculated, how lenders assess borrowing capacity, what real-world figures look like, and how a second dwelling or granny flat can fit into the bigger financial picture.
Most homeowners assume tapping into equity for a second dwelling means a mountain of paperwork and a bank asking uncomfortable questions. It’s surprisingly not rocket science. It is one of the more straightforward things a lender will approve, provided the numbers are understood before the first phone call rather than during it.
Here is everything actually worth knowing before that call: what equity is and how much of it is genuinely usable, how the serviceability side of the equation works, what a real example looks like once the numbers are run, and where a granny flat fits into all of it once the finance question is settled.
What Equity Actually Is, and How Much of It You Can Actually Use
Equity is simply the gap between what a property is worth and what is still owed on it, but the figure that matters for borrowing is not the full gap. Most lenders will advance up to 80 per cent of a property’s current value before lenders mortgage insurance kicks in, and usable equity is calculated as that 80 per cent ceiling minus the existing loan balance. A home worth $800,000 with $440,000 still owed leaves $200,000 in usable equity under that formula, a figure that has nothing to do with how much the mortgage has been paid down beyond that threshold and everything to do with where the 80 per cent line actually sits.
How Does Equity Work When Buying a Second Home in Australia
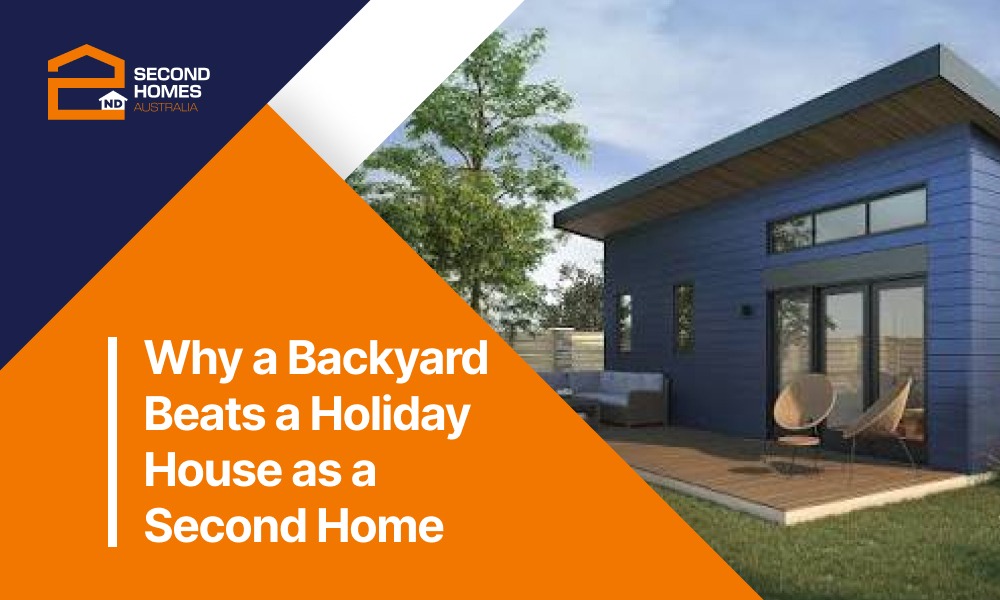
So how does equity work when buying a second home in Australia specifically, as opposed to any other use of a home loan top-up? A second dwelling built on land already owned skips a stamp duty bill entirely, since no new title changes hands, and it is a fundamentally different conversation to a fresh mortgage on a separate property because the security the bank already holds simply gets drawn against further. Once the dwelling is tenanted, many lenders will also factor a portion of the expected rental income into borrowing capacity, something that does not apply to an equity drawdown used for a renovation or any purpose that does not generate its own income.
The Serviceability Check Most Homeowners Forget About
Having usable equity on paper and being approved to borrow against it are two different things, and the gap between them catches people out more often than the equity calculation itself. APRA’s mortgage serviceability buffer, currently held at three percentage points, requires lenders to assess whether a borrower could still make repayments if the interest rate on the loan were three points higher than what is actually being offered. That buffer applies whether the new debt is for a separate investment property or equity drawn down for a second dwelling on the existing block, and it is exactly why two homeowners with identical usable equity figures can walk away from the same lender with very different approved amounts. A homeowner with a higher income relative to existing debt clears that buffer comfortably. Someone closer to their borrowing ceiling on the original mortgage may find the bank approves less than the equity figure alone would suggest, which is worth knowing before getting attached to a specific build price.
What the Numbers Actually Look Like on a Real Property
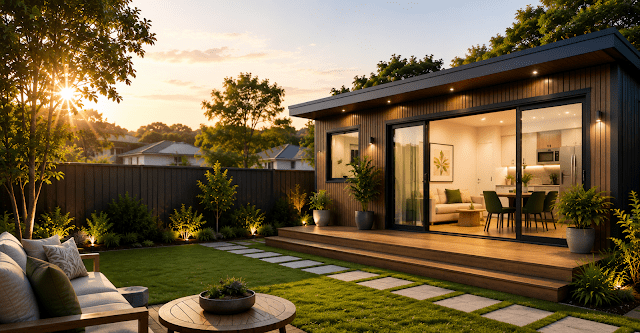
Picture a homeowner in Melbourne’s northern suburbs whose property is valued at $850,000 with $450,000 remaining on the mortgage. Usable equity under the 80 per cent formula comes to roughly $230,000, comfortably covering a turnkey second dwelling build. Once complete and tenanted, a two-bedroom dwelling in a comparable suburb renting in the vicinity of $500 a week generates in the order of $26,000 a year before expenses, a figure many lenders will partly factor into serviceability once a lease is in place, which is often what turns a borderline approval into a comfortable one.
Granny Flats Melbourne: What They Actually Cost and Return
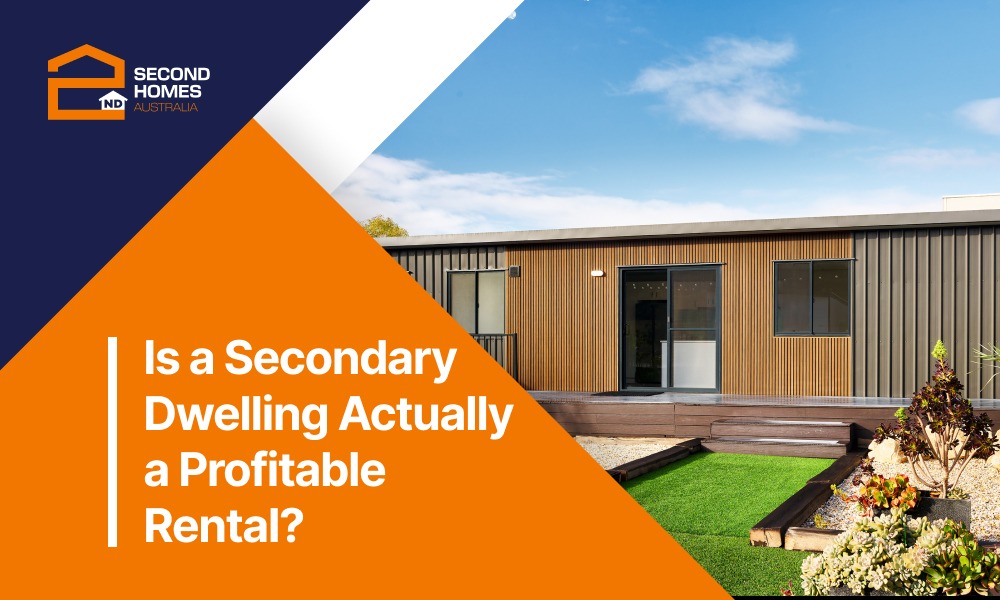
Granny flats in Melbourne currently range from roughly $150,000 for a compact one-bedroom build up to $255,000 for a larger two-bedroom design, depending on size and finish. Rental returns on a well-located, well-built dwelling typically land between $300 and $550 a week depending on the suburb and specification, and a compliant, quality build generally adds somewhere between $100,000 and $150,000 to the underlying property’s value on top of whatever it earns in rent. Site-built construction, concrete slab to steel frame, tends to hold that value more reliably than a modular or relocatable alternative, since lenders, valuers and tenants all treat a permanent structure differently to one that arrived largely pre-assembled.
Second Homes Australia: Site-Built From the Ground Up
Second homes in Australia increasingly means exactly this: a permanent dwelling on an existing block, funded through equity rather than fresh savings or a business loan, built to the same standard as the house already on the property. Second Homes Australia builds precisely that across Melbourne, concrete slab to steel frame, with turnkey packages from $150,000 and a ten-year structural warranty behind every build, and a free property assessment is the fastest way to find out what a specific block’s usable equity could actually fund.
Working out the usable equity figure, and what a lender will actually approve against it once the serviceability buffer is applied, is worth doing before a single floor plan is chosen, not after. The backyard sitting behind most Melbourne homes right now already has the answer to most of these questions. It just has not been asked yet.